Learning Balance Transfers
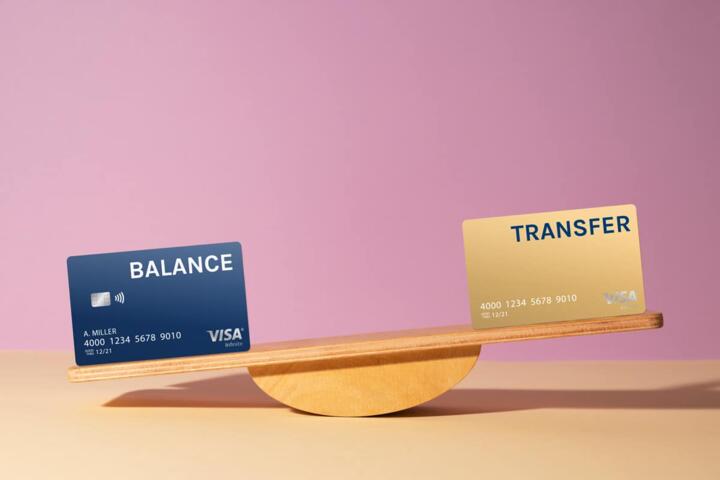
A balance transfer card lets you move debt from one credit card to another, usually to benefit from a low or zero percent interest rate for a specific period. For example, some cards offer 0% APR on balance transfers for 12 to 21 months. This means you don't pay interest on transferred debt during that time. Capital One and Chase often feature such offers, but terms vary widely.
Balance transfers aren't free though. Typically, there’s a fee around 3% to 5% of the transferred amount. That’s $90 to $150 on a $3,000 transfer. You trade upfront costs for potential interest savings. This becomes appealing when original cards charge 18% or more APR. Thus, a 0% balance transfer for 18 months could save hundreds or thousands in interest if handled correctly.
Transfers require approval and credit checks; not all balances or card types qualify. Store cards, for example, often cannot be transferred. Furthermore, some providers exclude promotional or recently opened cards.
Common Misunderstandings
Many assume balance transfers erase debt. They only postpone interest accumulation. The interest-free period usually lasts from 6 to 21 months — depending on issuer and offer. After this, the remaining balance incurs the regular APR. Miss the deadline, and the accrued interest kicks in retroactively in some cases.
Some people miss that new purchases on the transfer card typically don’t enjoy the zero percent promo. Purchases often bear normal APR, adding to debt stress if not paid off promptly. New charges can collide unfavorably with lingering transferred balances if minimum payments slip or confusion about interest categories persists.
Also, credit score impact gets overlooked. Applying typically results in hard inquiries slightly reducing your score for a few months. Then, your credit utilization changes, which can raise or lower scores depending on circumstance. The key: balance transfers don’t guarantee credit improvement unless you reduce overall debt and pay consistently.
Steps to Use Them Right
Choose the Right Card
Look beyond the 0% intro rate. Examine the length of the promo period, transfer fees, and standard APR post-intro. Cards like Citi’s Double Cash or Discover it Balance Transfer offer around 15-21 months with 3% fees. Compare these with shorter promos offering lower fees but higher APRs afterward. NerdWallet and Bankrate provide detailed, up-to-date card comparisons that help make a granular choice.
Calculate Transfer Fees vs Savings
Balance transfer fees are money upfront. If you owe $5,000 and pay 4% ($200) to transfer, your math must prove interest savings exceed $200 within the promo’s interest-free window or better than your current interest. Online calculators (like the one at CreditCards.com) assist in quantifying total costs and benefits precisely.
Transfer Strategically
Transfer the highest-interest balances first. Prioritize credit cards charging 20% or more. Avoid transferring balances close to payoff — fees might outweigh savings. Split balances if the transfer card limits maximum transfers or has low credit limits, telling banks of your clear payoff intention.
Pay More Than Minimum
Minimum payments only cover part of the principal during promos, occasionally just fees or small amounts of the balance. Paying more reduces principal faster, minimizing post-promo interest. Setting up automated payments ensures deadlines aren’t missed—a detail I found invaluable with the Chase Slate card in 2022.
Track Promo Expiry Dates
Always note the exact month the interest-free period ends. At expiry, any balance transfers accrue interest retroactively unless fully paid. Alerts on phone calendars or budgeting apps prevent surprise charges. I still rely on Google Calendar reminders to avoid missing these.
Avoid New Purchases During the Promo
New charges often carry regular APR and might complicate your overall payment priorities. Using another card for purchases during the promo period compartmentalizes debt, helping control what accrues interest. This is easier said than done, though, if you don’t have multiple cards or disciplined spending habits.
Transfer Multiple Balances
If you’re juggling debt across several cards, spreading the transfers across one or two new cards with generous limits can reduce interest payments broadly. Some credit cards cap monthly or lifetime transfer amounts. A strategic multi-card approach can circumvent this but requires more tracking.
Monitor Your Credit Score
Regularly check your credit through free services like Credit Karma or via free annual credit report checks. Watching the score helps measure if your balance transfers and repayments positively affect credit utilization or if adjustments are needed before applying for another card.
Use Balance Transfer Calculators
These tools weigh fees, lengths, and rates to model your specific payoff scenarios. It’s surprising how often a seemingly good deal isn’t financially attractive when you factor everything, including some annoying fine print, from my 2023 review experience on Credit Sesame.
Real-Life Examples
A consumer carried $7,500 at 22% APR on three cards. They used a Chase Slate card offering 15 months at 0% with a 3% transfer fee. The transferred balance cost $225 upfront. By budgeting $500 monthly, they cleared the $7,500 before promo expiry, avoiding more than $1,500 in interest compared to their original cards.
Another person transferred a $2,600 store card balance at 24% to a Citi Double Cash with 18 months promo at 0% and a 3% fee. The fee was $78. They overshot the payoff deadline, and Citi charged backdated interest amounting to $350. The financial hit reinforced the need for strict timeline adherence.
Balance Transfer Checklist
| Step | Action | Notes | Tools |
|---|---|---|---|
| 1 | Compare rates | Check APR, fees, term | NerdWallet, Bankrate |
| 2 | Calculate savings | Weigh fee vs interest | CreditCards.com calc |
| 3 | Initiate transfer | Confirm limits & eligibility | Issuer portal |
| 4 | Schedule payments | Automate more than minimum | Bank app, Mint |
| 5 | Track promo end | Set reminders, check statements | Calendar, credit app |
Mistakes and Fixes
Transferring without a clear payoff plan wastes money. Some ignore fees or transfer to multiple cards impulsively, thinking all will be forgiven. The fix: always draft a timeline and payment plan first. Misunderstanding promo terms leads to surprise high-interest bills post-promo; read every sentence before transferring. Late or missed payments often void the 0% APR, reverting balances to high rates. Set alerts, automate payments.
Using the transfer card for new, high-interest purchases without planning complicates debt tracking. Solution: separate cards for different purposes during the promo period. Finally, some apply for cards without checking credit score or income limits, leading to declined transfers, which could ding credit further.
FAQ
What is a balance transfer card?
It’s a credit card offering a low or zero percent interest rate on transferred balances for a limited time to help manage existing credit debt.
Are balance transfer fees always charged?
Usually, yes. Most issuers charge 3% to 5% of the transferred amount, although some promotions waive these fees temporarily.
Can I transfer balances from any card?
No. Some cards, especially store-specific ones or recently opened accounts, typically cannot be transferred.
What happens after the promo period ends?
The remaining balance accrues interest at the card’s standard APR, which can be high, so paying off before expiry is advised.
Does applying for a balance transfer affect my credit score?
Yes, through a hard inquiry and changes in credit utilization, which can temporarily lower your score but might improve with consistent repayments.
Author's Insight
I have personally used balance transfer cards during a crunch in 2022, juggling debt across multiple credit lines. The 0% periods gave me breathing room, but only because I tracked deadlines obsessively and paid above the minimum. I saw firsthand how missing even one payment erased interest savings, which, frankly, most people skip. My best advice: treat the balance transfer like a temporary loan, not a magic fix.
Key Points
Balance transfer cards stand as a strategic tool to cut interest costs when managed precisely. Choose offers after calculating fees versus interest saved, map payment plans that clear debt before rates return, and keep track of expiry dates. Avoid new purchases on the transfer card and monitor credit impact closely. Treat the transfer as a strict timeline challenge, and you can substantially reduce credit card debt burden.